Buying Your First Home in Colorado? Here Are 4 Steps to Get Started!
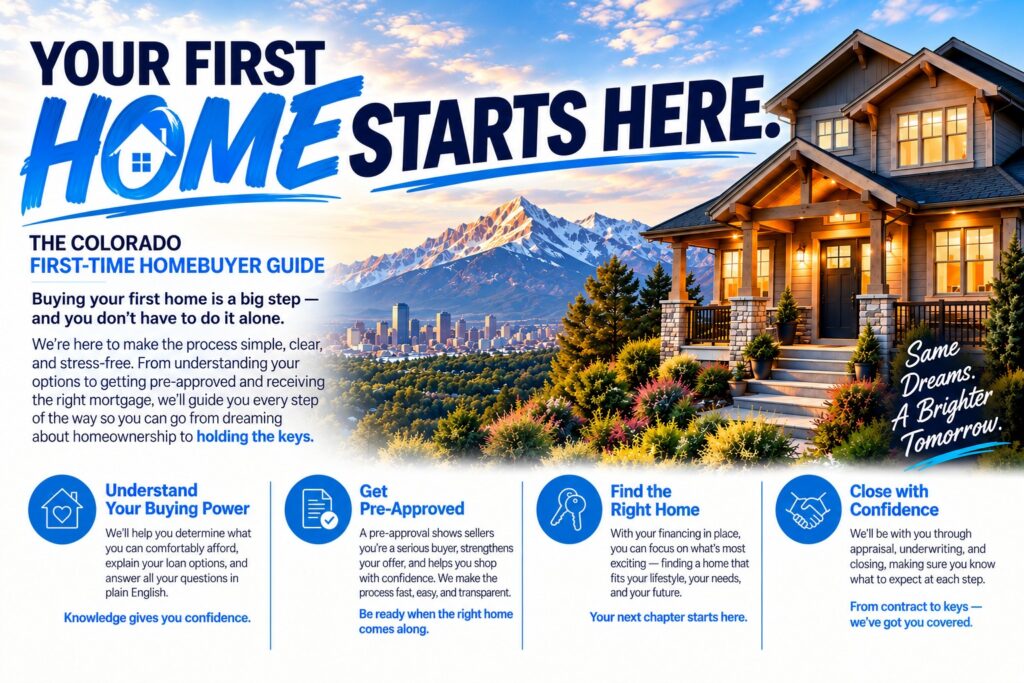
Your First Home Starts Here — From Dreaming About Homeownership to Holding the Keys!
So, you've been thinking about buying your first home.
Maybe you've been scrolling through Zillow, checking out houses in your favorite Colorado neighborhoods, or driving past a FOR SALE sign and thinking...
"Man, I could really see myself living there!"
But then the questions start popping up.
"What's the first thing I should do if I want to buy a house in Colorado?"
"How much house can I actually afford?"
"Should I get pre-approved before I start looking at homes?"
"What's the difference between pre-qualification and pre-approval?"
"Can I get pre-approved before I find a house?"
"What happens after the seller accepts my offer?"
"How long does it take to close on a house in Colorado?"
"And how do I know I'm making the right decisions along the way?"
Sound familiar?
Buying your first home is exciting, but when you've never done something before, it's hard to know what you don't know!
Here's the good news.
BUYING YOUR FIRST HOME DOESN'T HAVE TO BE COMPLICATED!
I've spent 25 years helping people navigate the Colorado mortgage market, and one thing I've learned is that confidence comes from understanding what happens next.
So let's break the process down into four straightforward steps.
Step 1: Understand Your Buying Power — What Can You Comfortably Afford?
Before you start falling in love with houses online, let's figure out what makes sense for your budget.
And notice I said what makes sense for your budget, not simply the biggest loan a lender might approve.
Those are two VERY different things!
When we look at your buying power, we'll talk about your income, monthly debts, savings, and financial goals.
We'll also estimate your total monthly mortgage payment, including:
- Principal and interest
- Property taxes
- Homeowners insurance
- Mortgage insurance, if applicable
- HOA dues, if applicable
And here in Colorado, we also want to pay attention to things like metro district taxes and property-specific insurance expenses.
Two homes with the same purchase price can have noticeably different monthly payments!
Why does all this matter?
Because buying a house shouldn't mean giving up everything else you love doing!
If you enjoy traveling, spending weekends in the mountains, or simply having some financial breathing room, I want those things to be part of our conversation.
Troy's Take: Just because you CAN qualify for a certain amount doesn't mean you SHOULD spend that much. The right home is one you love AND can comfortably afford!
Step 2: Get Pre-Approved — Know Where You Stand Before Shopping!
Now that we've looked at your budget, let's talk about mortgage pre-approval.
A pre-approval generally involves a lender reviewing your financial information to determine potential financing options and a loan amount, subject to additional requirements.
We typically review your income, employment, credit, assets, and existing financial obligations.
Pre-Qualification vs. Pre-Approval — What's the Difference?
Great question!
Pre-qualification is generally an initial assessment based on financial information you provide over the phone, sometimes with limited verification.
Pre-approval usually involves a more detailed review of your financial situation and supporting documentation.
The exact process varies by lender, and neither is a guarantee of final loan approval.
But a strong pre-approval can help you understand your price range and demonstrate to sellers that you've taken important steps toward securing financing.
Should You Get Pre-Approved Before Finding a House?
ABSOLUTELY!
In fact, that's usually the best time to do it, and most real estate agents require it.
Getting pre-approved before shopping helps you identify potential financing concerns early and gives you a clearer understanding of what you may be able to purchase.
And here's something I want first-time buyers to know.
Getting pre-approved doesn't mean you're obligated to buy a house tomorrow!
It simply helps you prepare.
At 5280 Financial Group, we offer same-day pre-approvals when the necessary information and documentation are available.
Troy's Take: Don't wait until you find your dream house to figure out whether the financing works. Let's get the numbers together FIRST!
Step 3: Find the Right Home — NOW the Fun Begins!
Alright, my friend.
You've reviewed your budget.
You've explored your financing options.
You've gotten pre-approved.
NOW THE FUN BEGINS — LET'S GO SHOPPING!
This is where your real estate agent steps into the spotlight.
You'll start touring homes, exploring neighborhoods, comparing properties, and hopefully finding a place that feels just right.
Maybe you're looking in Denver, Littleton, Parker, Castle Rock, Highlands Ranch, Aurora, Broomfield, or somewhere else along Colorado's Front Range.
Every community has its own housing options, lifestyle considerations, and expenses.
And remember, the purchase price is only part of the equation.
Property taxes, homeowners insurance, metro districts, and HOA dues can affect your monthly payment.
That's why your real estate agent and mortgage broker should be communicating throughout your home search.
When you find a property you love, we'll revisit the numbers for THAT specific home.
What Happens When You Find the One?
Your real estate agent helps you prepare an offer based on the property's price, condition, local market activity, and your goals.
The offer generally includes important terms involving the purchase price, earnest money, inspection deadlines, financing, and closing date.
Your agent helps you navigate those terms and negotiations.
And your mortgage broker?
We're here to help ensure the financing side of the transaction makes sense.
Troy's Take: Don't just shop for the prettiest kitchen or biggest backyard. Shop for a home that makes sense for your life AND your wallet!
Step 4: Close With Confidence — From Contract to Keys!
You've found the home.
Your offer has been accepted.
You're getting excited!
Now what?
This is when your mortgage team, real estate agent, title company, and other professionals work together to move the transaction toward closing.
Depending on the property and loan program, the remaining steps may include:
- Home inspection and any related negotiations
- Property appraisal, when required
- Final mortgage underwriting
- Homeowners insurance arrangements
- Title review and closing preparations
Your lender may also request additional documents along the way.
Don't let that worry you. That's a normal part of the mortgage process!
How Long Does It Take to Close on a House in Colorado?
It depends on several factors, including underwriting, documentation, appraisal requirements, title work, and contract deadlines.
Some purchases close relatively quickly. Others take more time.
At 5280 Financial Group, our average clear-to-close timeline is 11 calendar days.
Keep in mind that clear-to-close isn't the same as getting your keys. Final disclosures, signing, funding, and other closing requirements still need to be completed.
And no specific timeline can be guaranteed for every transaction.
What Happens on Closing Day?
Before closing, you'll receive a Closing Disclosure outlining your final loan terms, closing costs, and funds needed to complete the purchase.
For most covered mortgages, the initial Closing Disclosure must be received at least three business days before consummation.
You'll have an opportunity to review everything and ask questions before signing.
Once the transaction is completed, funded, and the applicable requirements for possession have been satisfied?
IT'S TIME TO GET THOSE KEYS!
At 5280 Financial Group, you'll work directly with me and my dedicated processor throughout the process.
Troy's Take: A smooth closing doesn't happen by accident. It takes preparation, communication, and a team working together to make things happen!
How Do You Know You're Making the Right Decisions?
Here's something I tell people all the time.
You don't have to know everything about buying a home.
You just need to understand the decisions you're being asked to make.
If you're uncomfortable with your estimated monthly payment, let's talk about it.
If you don't understand a loan term, let's explain it.
And if the numbers simply don't make sense?
WE DON'T FORCE THE DEAL!
Sometimes a different home, another financing option, or waiting a little longer may be the smarter decision.
My job isn't to convince you to buy a house.
It's to help you make a smart financial decision about buying a HOME!
The Bottom Line — Four Steps to Your First Home!
Here's what I want you to remember.
You don't need to know everything about mortgages.
You don't need to understand every document before asking for help.
And you certainly don't have to figure out the homebuying process on your own.
Just remember these four steps:
- Understand your buying power.
- Get pre-approved.
- Find the right home.
- Close with confidence.
Four steps.
One exciting goal.
And a team helping you along the way!
At 5280 Financial Group, we LISTEN first and LEND second.
Because buying your first home isn't just another transaction.
It's the beginning of a pretty exciting new chapter!
Ready to Take That First Step?
Maybe you've been thinking about buying your first home for months.
Maybe you're wondering what you can afford.
Or maybe you're just not sure where to begin.
Wherever you are in the process, let's have a conversation!
No pressure. No complicated mortgage jargon. Just honest answers and a plan that makes sense for YOU.
YOUR FIRST HOME STARTS HERE!